backtesting
Paper Trading vs Backtesting: What Each One Can and Cannot Prove
Both look like validation. Neither is sufficient alone. Here's exactly what each test can and cannot prove — and why confusing them costs traders real money.
backtesting
Both look like validation. Neither is sufficient alone. Here's exactly what each test can and cannot prove — and why confusing them costs traders real money.
metrics
Three metrics, three different definitions of risk — and optimizing for the wrong one can make a losing strategy look brilliant. Here's which one actually matters for your strategy.
backtesting
Suspecting your backtest is overfit is not the same as knowing. The PBO score turns that suspicion into a number — here's how it works and what to do with it.
statistics
A Sharpe of 2.1 sounds bulletproof. The Deflated Sharpe Ratio shows it's probably not. Here's the math that exposes why.
backtesting
Run enough backtests and you'll find a 'winning' strategy by pure chance. That's not edge — that's p-hacking, and it's more common than you think.
Walk-Forward Analysis
A single in-sample/out-of-sample split feels rigorous — it isn't. Walk-forward analysis is the only test that mimics how a strategy actually ages in the market.
Monte Carlo
Your backtest shows one equity curve. Reality will hand you thousands of possible ones. Monte Carlo simulation maps that entire landscape — but most traders misread the map.
prop firms
A high Sharpe ratio and a smooth equity curve aren't enough to pass an FTMO challenge. Here's how to map your backtest statistics to prop-firm rules before you risk the fee.
overfitting
You ran the optimizer, found the best settings, and the backtest looks great. That's exactly the problem. Here's why optimized strategies die in live trading — and the two tests that catch it first.
backtesting
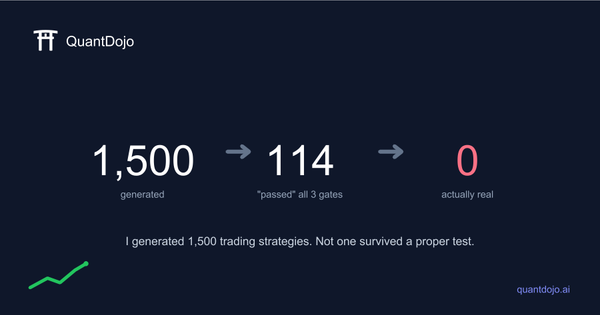
A hands-on demonstration of why in-sample / out-of-sample / holdout testing isn't enough to catch overfitting — and the statistics that actually are.